How Much Deposit Do You Actually Need to Buy a House in 2026?
The legal minimum is 5% — but the average first-time buyer in England puts down £63,855. Here's why the gap is so wide, how long it actually takes to save by region, and what gifted deposits and family springboard mortgages really involve.
Technically, you can buy a home in the UK with nothing down. In practice, the average first-time buyer in England puts down £63,855. The gap between "technically possible" and "what people actually pay" is the real question — and the honest answer depends on where you're buying, how fast you can save, and whether anyone's willing to help.
Key Takeaways
The legal minimum most lenders ask for is 5% of the purchase price, but the average first-time buyer deposit in England is £63,855 — closer to 25–30% of the average first-time buyer home.
Deposit size varies enormously by nation: £63,855 in England versus £40,528 in Northern Ireland, £35,572 in Wales, and £30,551 in Scotland.
At current saving rates, a 5% deposit on an average first-time buyer home takes roughly 5.1 years to save from scratch; a 2% deposit takes about 2.1 years — but a Londoner saving 10% of net pay needs around 9 years, versus 4 years in the North.
Gifted deposits are common and lender-accepted, but must be declared non-repayable in writing — undeclared gifts can be treated as mortgage fraud, and each individual can gift up to £3,000 a year without inheritance tax implications.
Family-backed products like Barclays' Family Springboard and Halifax's Family Boost let a relative secure your mortgage with their own savings instead of a cash gift — the money is locked for 3–5 years, then returned with interest if you keep up repayments.
At a Glance — Deposit Size vs Time to Save
Deposit Size
Example (on £226,000 home)
Typical Time to Save*
2%
£4,520
~2.1 years
5%
£11,300
7 min read·September 21, 2026·0
James Calloway
Writer
~5.1 years
10%
£22,600
~4 years 4 months (at £500/month, 5% interest)
Average FTB deposit (England)
£63,855
Varies widely by income and region
*Based on average national saving rates and salaries — your own timeline depends heavily on income, rent, and location. See regional variation below.
Why the "Minimum" and the "Average" Are So Far Apart
Most lenders will accept a 5% deposit, and Skipton's Track Record Mortgage will accept none at all — we cover both routes in full in First-Time Buyer's Guide to Mortgages in the UK (2026 Edition). But most first-time buyers don't borrow at the legal minimum. Bigger deposits unlock meaningfully better rates, and many buyers — especially those who've had help from family — put down 15–25% rather than 5%. That's why the "average" deposit in England, £63,855, looks so much larger than the 5% minimum: it's blending buyers stretching to the smallest deposit possible with buyers who've saved for years or received substantial help.
Regional Reality: Same Country, Very Different Numbers
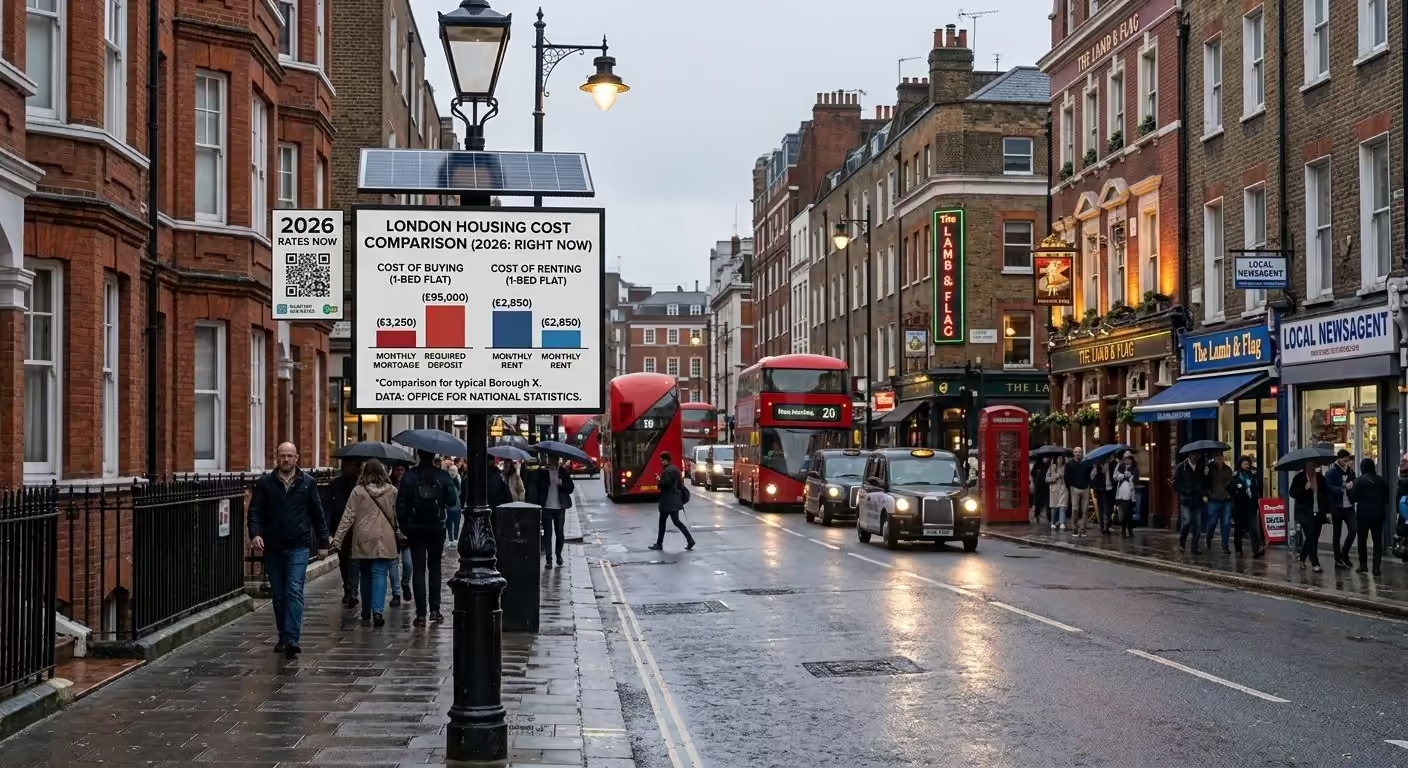
Deposit size is really a house-price problem wearing a different hat. Average first-time buyer prices range from around £145,000 in the North East to over £510,000–£540,000 in London, with Scotland (£195,000) and Wales (£210,000) in between. A 10% deposit in London — roughly £51,000 — is more than four times the 10% deposit needed in the North East. That gap shows up directly in the national deposit averages: £63,855 in England is pulled upward by London and the South East, while Scotland's £30,551 average reflects a materially cheaper market, not necessarily more cautious buyers.
Saving timelines follow the same pattern. Someone in Aberdeen can realistically save a deposit in under 4 years; in St Albans, the average stretches past 16 years. A Londoner saving 10% of net pay needs roughly 9 years to reach a typical deposit; the same saving rate gets someone in the North there in about 4.
💡 Model your own numbers, not the national average: run your income, target area, and monthly saving rate through our Mortgage Calculator to see what deposit and monthly payment are actually realistic for you.
Gifted Deposits: The Most Common Shortcut
A meaningful share of first-time buyers get some or all of their deposit from family. Lenders are generally comfortable with this, but they're strict about the paperwork: the person gifting the money must sign a letter confirming the gift is non-repayable, that they won't take a stake in the property, and that they won't live there. Lenders typically accept gifts from parents, grandparents, siblings, and other close relatives (and sometimes family friends), but each donor needs their own letter and proof of where the money came from.
Two things catch people out. First, failing to declare a gift to your lender or solicitor can be treated as mortgage fraud — it must go on record, even if it feels like "just a family matter." Second, gifts above £3,000 per person per year can have inheritance tax implications if the donor dies within seven years, though this rarely changes whether the gift itself is usable for a deposit.
When Family Wants to Help Without Giving Cash Away
If a relative wants to help but doesn't want to hand over a lump sum permanently, family-backed mortgages are the middle ground. With Barclays' Family Springboard Mortgage, a family member deposits savings equal to 10% of the purchase price into a linked account instead of gifting it — that money is locked for five years and returned with interest, as long as the buyer keeps up their repayments. Halifax's Family Boost works similarly but releases the funds after three years instead of five, and allows multiple family members to contribute to the same linked account. Both let a first-time buyer borrow effectively without their own deposit, while the helper's money stays theirs — it's just tied up, not given away.
What This Means for You
There's no single number that answers "how much deposit do I need" — there's a 5% legal minimum, a national average nearly six times higher, and a huge regional swing in between. The realistic move is to work backward from your own target area's prices, your own saving rate, and whether family help (gifted or springboard-style) is genuinely on the table — rather than anchoring on either the 5% headline or the £63,855 national average, neither of which may reflect your actual situation.
What You Should Do Next
Check average first-time buyer prices in your specific target area, not the national average — the gap between regions is enormous
Work out your realistic monthly saving rate and how long a 5%, 10%, and 15% deposit would each take at that pace
If family can help, discuss upfront whether it'll be a gift (with a signed letter) or a springboard/boost-style product — the paperwork and commitment differ
Declare any gifted deposit to your lender and solicitor in writing, in full, before you apply
The 5% minimum deposit gets you in the door; the £63,855 average is what buyers who've saved longer or had family help actually put down. Where you're buying changes both numbers dramatically — a 10% deposit is £51,000 in London and roughly a quarter of that in the North East. Work out your own realistic deposit and timeline before comparing yourself to either the minimum or the average — both can be misleading on their own.
FAQ
What's the actual minimum deposit to buy a house in the UK?
Most lenders ask for at least 5% of the purchase price. A small number of 100% mortgages, like Skipton's Track Record Mortgage, require no deposit at all for eligible buyers.
Why is the average first-time buyer deposit so much higher than 5%?
Because it blends buyers borrowing at the minimum with buyers who've saved for years or received family help, and because it's skewed upward by expensive regions like London and the South East.
Can my parents just give me money for a deposit?
Yes, but it must be declared to your lender and solicitor as a non-repayable gift, backed by a signed letter. Failing to declare it can be treated as mortgage fraud.
What's the difference between a gifted deposit and a family springboard mortgage?
A gift is handed over permanently. With a springboard or family boost mortgage, a relative's savings are locked in a linked account for 3–5 years and returned to them with interest — the money isn't given away.
This article is for informational purposes only and does not constitute financial advice. House prices, deposit requirements, and lender criteria change frequently — always check current figures and terms directly with a lender or independent mortgage broker before applying.
Still with us?
Take the community poll, test yourself with the quiz — or both.
Topic hubs
Browse more articles in these categories and tags.
James Calloway is a personal finance writer and real estate strategist covering housing markets across the UK, US, and beyond. With a decade of experience translating complex financial decisions into plain language, he believes the best money advice sounds like a candid conversation — not a lecture.
125K followers89 articles
Related reading
Related articles
Closely related by shared tags and categories — continue in this topic cluster.